Triumph Financial smashes targets as trucking bets pay off
CEO Aaron Graft hails 37.8% revenue growth and 43% factoring margin in Q3 as investments deliver
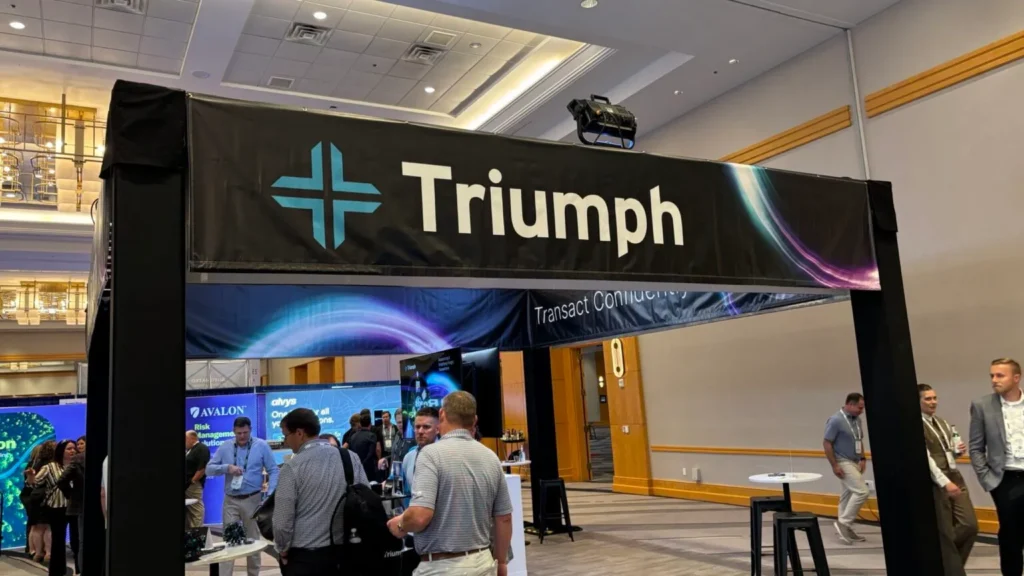
Aaron Graft, CEO of Triumph Financial, struck an unmistakably triumphant tone in his latest quarterly letter to shareholders, as the company surpassed its own performance benchmarks across key business segments. Triumph Financial, traded on the NYSE under the ticker TFIN, has spent years transforming itself from a conventional bank into a comprehensive financial services provider tailored for the trucking industry.
The company’s strategy rests on four core pillars: factoring, payments, business intelligence, and digital financial tools for drivers and small fleets. Factoring, the original business line, remains central, but Triumph has expanded its offerings through strategic acquisitions. In 2021, it acquired HubTran to bolster its payments infrastructure, followed by the purchase of Green Sheets last year to enhance its intelligence services. This year, the company launched LoadPay, a digital wallet designed for independent operators and small fleets.
Record growth in transportation revenue and margins: Triumph Financial
The third-quarter earnings report revealed significant progress, with Triumph exceeding its long-term targets in several critical areas. Transportation revenue surged by 37.8%, more than double the company’s 15% growth goal. Approximately one-third of this increase was organic, indicating that the gains were not solely driven by external factors like a stronger freight market or rising diesel prices.
Factoring operating margins also outperformed expectations, reaching 43%, three percentage points above the company’s 40% target. Meanwhile, payments EBITDA, excluding the LoadPay wallet, climbed to 39%, up from 34% in the previous quarter. However, not all segments delivered equally strong results. Intelligence revenue, tied to the Green Sheets acquisition, fell slightly to $2.4 million, leading Graft to remove the 85% gross margin target from the company’s “North Star Metrics.”
In his letter, Graft addressed the company’s long-term strategy, writing, “We told investors we would invest through the freight cycle, and we did exactly that. Not everyone agreed with the strategy, but we were true to our word.” He emphasized that the focus now shifts to converting these investments into sustained earnings growth, aiming to demonstrate the returns on the company’s multi-year build-out.
Stock struggles contrast with operational success
Despite the strong operational performance, Triumph Financial’s stock has faced challenges, declining by 43.5% over the past five years. This downturn reflects investor skepticism during a period of heavy investment, which temporarily weighed on profitability. However, the latest quarterly results suggest that the company’s strategy may finally be gaining traction.
Graft also highlighted broader shifts in the freight market, noting that the industry is transitioning from a landscape of abundant capacity to one where trusted, deployable capacity is the scarce resource. Triumph’s financial tools position it as a key partner for carriers navigating this volatility. As Graft put it, the company is now focused on “translating that potential into earnings performance consistent with our historical results and beyond.” With the third quarter’s strong numbers, investors may be increasingly inclined to take that promise seriously.
Sign up free to ask CAMAL AI for a summary, the key points or anything else about this story.
Related stories
CAMAL AI
 Financial Ports Newsletter
The maritime economy, every morning
Ports, shipping and freight markets in one short email. Free.