Houston Freight Market Flips: From Softest to Second-Tightest in 14 Days
Tender rejections in Houston surged to 10.47% as spot rates jumped 37% week-over-week.
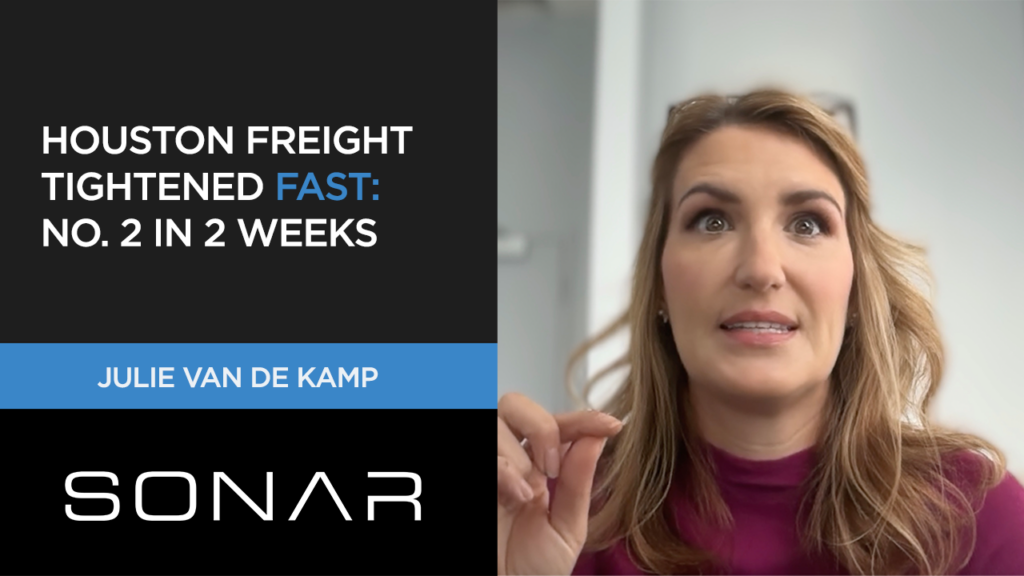
Houston’s truckload freight market has transformed rapidly, shifting from one of the most oversupplied in the U.S. to the second-fastest tightening among 135 tracked markets in under two weeks. The reversal, documented by FreightWaves SONAR data, stems from a sudden rise in tender rejections and climbing spot rates, signaling potential challenges for shippers and brokers moving goods out of the region.
As of September 22, tender rejections in Houston reached 10.47%, a near 3-point increase from the previous week and a 6-point jump compared to the same period last year. Three months earlier, rejection rates had been falling steadily, dropping roughly 8% over that stretch. The market’s Key Market Trend Index now registers 6.85, a level SONAR data classifies as extreme tightening.
Spot Rates Climb as Outbound Demand Intensifies: Freight Market
The most visible impact of the shift appears in spot rates. Van Trac spot conditions out of Houston surged 37% week-over-week, while tender volume rose nearly 2% during the same period. FreightWaves analyst Julie Van de Kamp noted the market continues to favor outbound shipments, a trend that typically drives rates higher as available capacity dwindles on key exit routes.
“It went from one of the loosest markets in the group to one of the tightest in the country in under two weeks. It’s now the second-ranked market out of 135 based on tightening trends.”
— Julie Van de Kamp, FreightWaves Analyst
Nationally, tender rejections remained above 14%, reflecting a modest month-over-month increase of about 1 percentage point. Van spot rates reached $3.42, marking a 4.27% rise over the same period.
Fuel and Intermodal Trends Complicate the Outlook
Rising fuel costs have added financial strain for carriers. On September 22, the diesel truck stop price stood at $6.54 per gallon, approaching a 52-week high and up sharply from roughly $4.90 in July. The Department of Energy’s price reached $6.29, slightly exceeding the previous 52-week high of $6.28.
Van de Kamp pointed to the widening retail-to-wholesale diesel spread—currently about $1.10—as a key factor, noting that carriers purchasing fuel at wholesale prices maintain a cost advantage. Meanwhile, intermodal contract rates climbed to $1.73, an 8% month-over-month increase, as freight volume continued shifting from road to rail.
The broader national freight market remains volatile. The Sonar STVI volume index rose 12.9% week-over-week as of September 22, though the increase followed an uneven pattern since Labor Day. Intermodal volume held steady, up about 2% week-over-week, while the IOTI ocean tender volume index dipped roughly 1%, suggesting the earlier surge in imports may have already peaked.
Sign up free to ask CAMAL AI for a summary, the key points or anything else about this story.
Related stories
CAMAL AI
 Financial Ports Newsletter
The maritime economy, every morning
Ports, shipping and freight markets in one short email. Free.