Fulfillment Margins Plummet: 9.7% to 0.6% in Just Three Months
Parcel shipping costs surged 13% year-over-year, outpacing GMV growth and squeezing operators ahead of peak season.
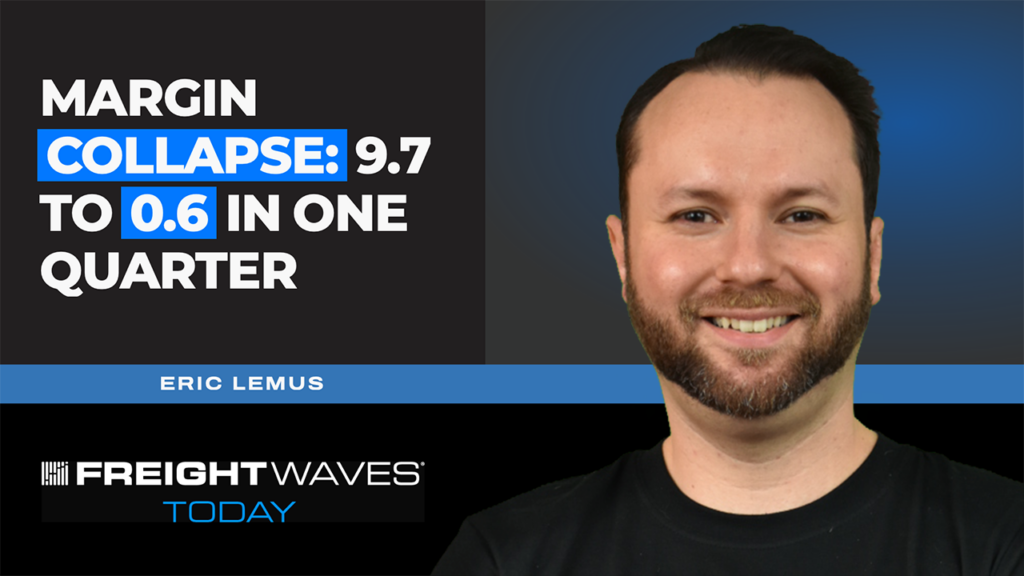
Fulfillment operators faced a brutal margin squeeze in the second quarter, with cushions collapsing from 9.7 points in April to just 0.6 points by the end of June, according to Deposco’s latest Commerce Signal report.
Eric Lemus, Vice President of Strategy and Analytics of Strategy and Analytics at Deposco, attributed the margin collapse to a fundamental disconnect between order volume and revenue. “Demand is slowing in dollars, but not necessarily in units,” he said. “Consumers are still buying, but operators are moving more units through their networks without seeing the reciprocal revenue growth as they anticipated.” The data underscores a growing challenge for the sector: while order volume growth climbed from roughly 4% to 8.8% during the quarter, GMV growth slowed from 15.4% to 13.4%, leaving operators caught between rising costs and stagnant top-line performance.
Why Shipping Costs Are Outpacing Revenue: Fulfillment
The 13% surge in parcel shipping costs by the end of Q2 was not an isolated spike but part of a broader trend. Lemus identified a combination of internal and structural factors behind the rise, including carrier mix, dimensional weights, and contracted rates. Energy costs, a persistent pressure point for logistics networks, further exacerbated the situation. Deposco’s forward forecast paints a grim picture for the remainder of the year, with parcel inflation expected to remain at least 12% year-over-year through Q4, before peak season surcharges are applied.
Those surcharges, which Lemus warned could average 6% or more, threaten to push margins into negative territory. “If you compound that with a pretty heightened environment of year-over-year inflation with parcels, this Q4 peak season will certainly show some pressure on the margins due to that carrier spend,” he said. The warning comes as operators prepare for the busiest shopping period of the year, where even minor cost increases can have outsized impacts on profitability.
The structural drivers of rising parcel costs extend beyond immediate operational decisions.
Lean Inventory Adds Another Layer of Risk
Inventory levels at the end of Q2 were the leanest in months, with days on hand closing at 89.3, a figure that raises concerns about stockouts and unfulfilled orders during peak season. Brands and third-party logistics providers ended the quarter with just 3.3 days of inventory coverage between them, an unusually narrow gap that leaves little room for error. While inventory levels have begun ticking up since July, Lemus cautioned that the rebound may be arriving too late to fully buffer demand.
Operators in the leanest inventory quartile face the most acute exposure, as they lack the buffer to absorb supply chain disruptions or unexpected demand spikes. “If you’re running lean, you’re more exposed to stockouts,” Lemus noted, adding that SKU-level inventory analysis is critical to identifying replenishment gaps before they become crises. This level of granularity allows operators to prioritise high-velocity items and avoid overstocking slow-moving products, a balancing act that becomes increasingly difficult as peak season approaches.
For brands and logistics providers, the consequences of lean inventory extend beyond immediate financial losses. Stockouts can erode customer loyalty, particularly in an era where consumers expect near-instantaneous fulfillment. A single unfulfilled order during peak season can result in long-term reputational damage, especially if competitors are able to meet demand more effectively. This dynamic has led many operators to reconsider their inventory strategies, with some opting to increase safety stock levels despite the associated carrying costs.
Deposco’s Commerce Signal report, which draws on live fulfillment transaction data from more than $80 billion in fulfilled GMV and over 4,000 brands and operators, also highlighted a potential lifeline for margin protection: carrier diversification.
Operators that adopted diversified carrier strategies reduced parcel spend by 21%, a significant advantage in an environment where every percentage point counts. “If you’re able to generate a more diversified carrier strategy, you’ll likely reduce your parcel spend by 21%,” Lemus said, urging operators to avoid anchoring forecasts to last year’s peak season data.
The report’s findings align with broader industry trends, where operators are increasingly turning to regional carriers, last-mile delivery partners, and even in-house logistics solutions to mitigate the impact of rising costs. This diversification not only reduces reliance on a single carrier but also provides flexibility to adapt to shifting market conditions. For example, regional carriers often offer lower rates for shorter distances, while last-mile partners can help reduce delivery times without incurring premium costs.
As operators prepare for Q4, the stakes could not be higher. The margin collapse observed in Q2 serves as a stark reminder of the fragility of fulfillment economics, where rising costs and shifting consumer behaviour can quickly erode profitability. With peak season surcharges looming and inventory levels still precarious, operators will need to act swiftly to protect their margins, or risk facing a Q4 defined by red ink.
For those seeking to navigate these challenges, Deposco recommends leveraging real-time analytics to monitor parcel spend, inventory levels, and order fulfillment performance, while also exploring carrier diversification strategies to mitigate cost pressures.
For further guidance, operators can refer to Deposco’s official resources, which offer insights into best practices for inventory management, carrier selection, and peak season preparedness. The firm’s Commerce Signal report, updated quarterly, remains one of the most comprehensive tools available for tracking fulfillment trends in real time.
Sign up free to ask CAMAL AI for a summary, the key points or anything else about this story.
Related stories
CAMAL AI
 Financial Ports Newsletter
The maritime economy, every morning
Ports, shipping and freight markets in one short email. Free.