Shipping’s crystal ball shatters: Why freight rates no longer predict
The once-reliable link between freight rates and global growth has collapsed, with a mere 3.3% correlation since 1954
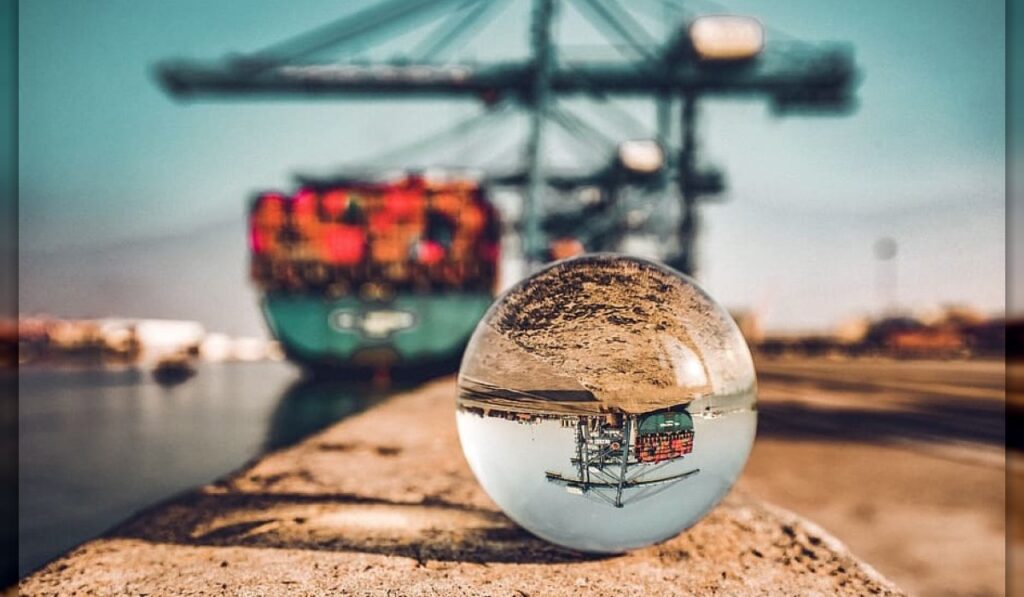
For decades, shipping was the world economy’s most reliable crystal ball, until now.
Martin Stopford, the veteran shipping economist behind Maritime Economics, tested the old adage by comparing annual growth in world industrial production with dry cargo freight rates between 1954 and 2025. The result? A correlation coefficient of just 3.3%, a figure so weak it suggests shipping markets have become almost useless as economic predictors. First published in 1988, Maritime Economics remains a foundational text in shipping research, shaping how economists and investors interpret freight markets.
Wars, sanctions, and congestion have turned shipping demand into a game of rerouting rather than growth. A cargo forced to sail thousands of extra miles around a chokepoint can inflate vessel demand without adding a single tonne to global trade. Tonne-miles, the distance cargo travels, have become as important as the volume of cargo itself, distorting the traditional relationship between shipping activity and economic output.
Adam Kent, Managing Director of Maritime Strategies International (MSI), notes that dry bulk demand, historically a proxy for emerging-market growth, has remained resilient despite three consecutive years of falling Chinese steel production. “Commodities are being sourced from further away,” Kent explains, “which keeps ships busy even when underlying industrial activity slows.” MSI, a UK-based consultancy, specialises in forecasting freight markets and advising investors, governments, and shipping firms on trends in dry bulk, tankers, and containers.
Its research is widely cited by financial institutions, including Citi, where Charles de Trenck previously led Asia transport research.
The resilience of dry bulk demand highlights a broader shift in global trade patterns. China, the world’s largest consumer of iron ore and coal, has seen its steel production decline for three consecutive years. Yet, the demand for ships has not mirrored this slowdown. Instead, longer supply chains, driven by sanctions, trade restrictions, and the search for alternative suppliers, have kept vessels in high demand. This decoupling of shipping activity from industrial output challenges long-held assumptions about the role of freight markets as economic barometers.
Tanker markets tell a similar story. Earnings no longer reflect oil consumption growth but rather energy security policies and sanctions. The International Monetary Fund (IMF), which has historically used shipping indicators as real-time measures of world trade, is now grappling with the limitations of these tools. Roar Adland, Global Head of Research at shipbroker SSY, puts it: “The claim that shipping is a predictor of the world economy was always dubious.".
The container conundrum: US demand vs. global reality: freight rates economy
Container shipping, once a window into Western consumer demand, has also lost its predictive power. The pandemic shifted supply chains from just-in-time to just-in-case inventories, while tariff frontloading and convoluted logistics have caused box volumes to diverge sharply from final consumer demand. Charles de Trenck, a former Citi transport analyst, argues that containers are now heavily influenced by outsized US consumption and government deficit spending, reducing their usefulness as a clean global indicator.
This divergence has made it increasingly difficult to use container shipping as a proxy for global economic health.
Freight rates, meanwhile, reflect not just cargo demand but also the number of available ships, a lagging indicator. Vessels ordered during a boom can arrive years later in a completely different economic environment. The multi-year lag between ordering and delivery means that today’s fleet size is often a relic of past market conditions, further distorting the relationship between freight rates and economic activity. With services dominating developed economies and AI-driven sectors generating less physical cargo, the disconnect between shipping activity and GDP growth is only set to widen.
The Baltic Dry Index, once a darling of economists, now serves as a cautionary tale. Researchers have long linked it to future industrial activity, but its signals are increasingly drowned out by geopolitical noise. The index, which tracks the cost of shipping dry bulk commodities like iron ore, coal, and grain, was once seen as a leading indicator of industrial production.
However, its reliability has been undermined by factors such as sanctions on Russian commodities, rerouting around conflict zones, and shifts in global supply chains. These distortions have made it harder for policymakers and investors to rely on the index as a predictor of economic trends.
Jan Hoffmann, Global Lead for Maritime Transport at the World Bank, warns that official trade statistics, delayed by customs declarations, are no match for the real-time visibility of ship movements. Yet even these “now-casts” of trade are losing their edge as rerouting and sanctions reshape global supply chains.
The World Bank, which works with governments to improve trade logistics, has increasingly turned to satellite data and AI-driven analytics to track ship movements. However, these tools are not immune to the distortions caused by geopolitical disruptions, making it harder to separate signal from noise in shipping data.
What this means for investors and policymakers
The erosion of shipping’s predictive power has significant implications for financial markets and economic policy. For decades, investors have used freight rates as a leading indicator of global growth, adjusting portfolios based on signals from the Baltic Dry Index or container freight benchmarks. However, the 3.3% correlation uncovered by Stopford’s research suggests that these tools are no longer reliable.
Richard Diamond, Principal at investor Castlewood Capital Partners, sums up the dilemma: “No, no, and yes.” His response reflects the uncertainty now facing investors: while shipping data can still offer insights, it must be interpreted with caution and supplemented by other indicators.
Policymakers, too, are grappling with the limitations of shipping data. Institutions like the IMF and the World Bank have traditionally relied on freight markets to gauge the health of global trade. However, the distortions caused by geopolitics, sanctions, and supply chain rerouting have made these tools less effective. As Hoffmann notes, the delay in official trade statistics, often months after goods have been shipped, further complicates efforts to monitor economic activity in real time. This lag leaves policymakers flying blind, unable to respond quickly to emerging trends.
For businesses, the breakdown in shipping’s predictive power underscores the need for more sophisticated forecasting tools. Companies that once relied on freight rates to anticipate demand for raw materials or finished goods must now incorporate a broader range of data, including geopolitical risk assessments, energy market trends, and real-time logistics tracking.
The shift from just-in-time to just-in-case inventories has also forced firms to hold larger stockpiles, increasing costs and reducing flexibility. In this environment, shipping data alone is no longer sufficient to guide decision-making.
As Stopford’s data shows, the 2020s have turned shipping from a leading indicator into a lagging one. The question now is whether the industry can adapt, or if the world economy will simply have to find a new forecasting tool. For now, the old crystal ball remains cracked, and those who still trust it may find themselves navigating in the dark.
For readers seeking to stay ahead of global economic trends, the message is clear: shipping data should be treated as one input among many, not as a standalone predictor. Institutions like the IMF, the World Bank, and UNCTAD continue to refine their models, but the era of relying on freight rates as a reliable economic barometer appears to be over. The future of forecasting may lie in a combination of real-time logistics data, geopolitical analysis, and traditional economic indicators, leaving shipping markets to dance to their own, increasingly unpredictable tune.
Sign up free to ask CAMAL AI for a summary, the key points or anything else about this story.
Related stories
CAMAL AI
 Financial Ports Newsletter
The maritime economy, every morning
Ports, shipping and freight markets in one short email. Free.