CPKC earnings jump 16% but fuel costs bite into margins
Canadian Pacific Kansas City reports C$4.22bn revenue for Q3, up 62% year-on-year, as fuel expenses surge
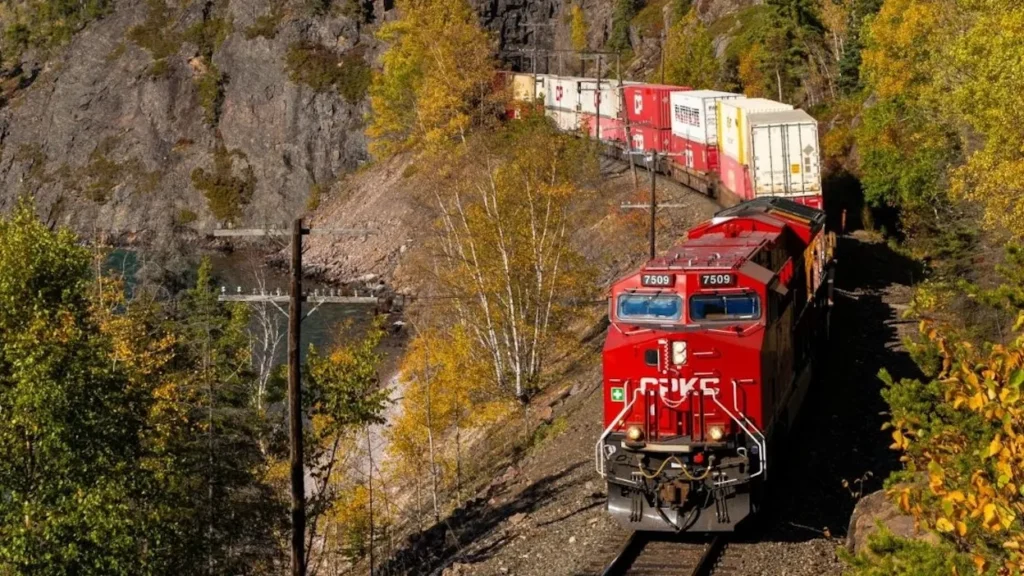
Canadian Pacific Kansas City (CPKC) reported a 16% increase in third-quarter core adjusted earnings per share, reaching 91 cents, as higher freight volumes and revenue growth across key segments offset rising fuel costs.
Energy, chemicals, and plastics revenue also saw gains, rising to $544 million from $499 million, and automotive revenue increased to $266 million from $244 million. Coal revenue remained nearly flat at $181 million.
The company’s operating income rose to $1.06 billion from $955 million, but expenses outpaced revenue growth. Fuel costs jumped to $475 million from $296 million, while compensation and benefits increased to $507 million from $441 million. The operating ratio, a key efficiency metric for railroads, worsened to 64.8% from 63.5%, with higher fuel prices adding 1.7 percentage points to the figure. The core adjusted operating ratio also deteriorated to 61.9% from 60.7%, reflecting the impact of rising costs.
Revenue growth across key segments: CPKC
Despite the revenue growth, net income attributable to controlling shareholders edged down slightly to $653 million from $655 million a year earlier. The decline was partly offset by a reduction in the weighted-average diluted share count, which fell to 877.6 million from 911.4 million. Reported earnings per share increased to 74 cents from 72 cents, while income tax expenses rose sharply to $319 million from $211 million, including a $67 million charge related to Canadian tax reassessments and a $12 million expense from a Mexican tax settlement.
CPKC also disclosed $12 million in advisory costs tied to its analysis of the proposed U.S. Surface Transportation Board review of the Union Pacific, Norfolk Southern merger. The company’s cash flow from operating activities improved to $1.10 billion from $905 million, though capital expenditures on property additions declined to $437 million from $613 million. CPKC used $1.02 billion to repurchase common shares during the quarter.
Keith Creel, President and Chief Executive of CPKC, attributed the results to the company’s operational discipline and network efficiency.
Creel added that the company’s «disciplined execution and a robust commercial pipeline» supported its confidence in meeting annual commitments, despite the challenges posed by higher fuel costs and macroeconomic uncertainties.
Margins under pressure despite strong volumes
The operating ratio, a critical benchmark for rail efficiency, remains a point of concern.
The U.S. Surface Transportation Board’s review of the proposed Union Pacific, Norfolk Southern merger could also shape CPKC’s strategic positioning. The $12 million in advisory costs disclosed by CPKC suggests the company is closely monitoring the regulatory landscape, which could have implications for competition and network access in the coming years. Industry observers will be watching for further developments, particularly as the merger review process unfolds.
CPKC’s leadership has signaled confidence in its ability to navigate the current economic environment, citing a «robust commercial pipeline» and operational discipline as key drivers of future performance. The company’s focus on high-growth segments, such as grain and intermodal, aligns with broader trends in North American trade, where railroads play a critical role in connecting agricultural producers with export markets and facilitating cross-border freight movements.
However, the outlook is not without risks. Fuel costs remain a wildcard, with energy price fluctuations capable of significantly impacting profitability. Additionally, the regulatory environment, particularly the ongoing review of the Union Pacific, Norfolk Southern merger, could introduce new competitive dynamics. CPKC’s ability to maintain its service advantage while managing costs will be crucial in sustaining its momentum through the remainder of the year.
For stakeholders, including investors, customers, and industry analysts, the next quarter will be pivotal. CPKC’s fourth-quarter results will provide further clarity on whether the company can sustain its revenue growth while mitigating the impact of rising costs. With the holiday season approaching, demand for rail services is expected to remain strong, particularly in intermodal and merchandise segments, which could help offset some of the margin pressures seen in the third quarter.
As the rail industry continues to evolve, CPKC’s integrated North American network positions it well to capitalize on cross-border trade opportunities. The company’s ability to adapt to shifting economic conditions while maintaining service reliability will be key to its long-term success. For now, the focus remains on executing its strategic priorities and delivering on its annual commitments, even as external challenges loom.
Sign up free to ask CAMAL AI for a summary, the key points or anything else about this story.
Related stories
CAMAL AI
 Financial Ports Newsletter
The maritime economy, every morning
Ports, shipping and freight markets in one short email. Free.