Hengli storms to top of global shipbuilding with 23.4% market share
Chinese yard secures 276 orders in nine months, leapfrogging South Korean and Japanese rivals
Hengli Heavy Industry has seized the crown as the world’s leading shipbuilder, capturing nearly a quarter of global newbuilding orders in the first nine months of 2026.
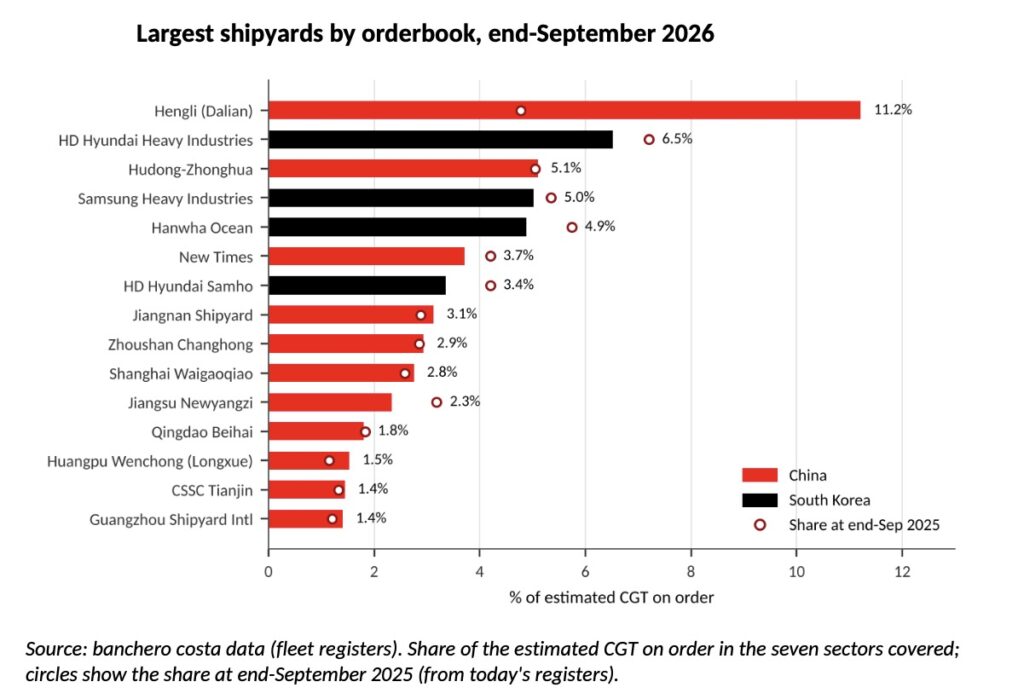
Banchero Costa’s latest figures reveal Hengli secured orders for 276 ships between January and September, representing 23.4% of all compensated gross tonnage (cgt) contracted across seven major merchant shipping sectors. The yard’s orderbook now stands at 485 ships, or 11.2% of the global total by cgt, more than any other single shipyard.
The transformation is staggering. Just four years ago, Hengli was a struggling entity, having acquired the failed STX Dalian shipyard in 2022. Deliveries were minimal, four ships in 2024 and 17 in 2025. This year, however, the yard has already delivered 62 ships in the first nine months, with another 99 slated for 2027 and an eye-watering 199 in 2028. On a cgt basis, Hengli alone is projected to account for 12.6% of all global deliveries in 2028 across the seven sectors.
From bankruptcy to dominance in four years: Hengli
The yard’s expansion has been equally aggressive. Hengli embarked on a RMB13.5bn ($1.9bn) investment programme, installing two of the world’s largest gantry cranes, each with a 2,000-tonne capacity and spanning 256 metres. The group is also vertically integrating, manufacturing its own marine engines and critical equipment to reduce reliance on third-party suppliers.
The financial rewards of Hengli’s turnaround are undeniable. Songfa, the yard’s Shanghai-listed parent, reported an attributable net profit of RMB6.6.67bn ($994m) in the first nine months of 2026, a 425% year-on-year surge. Third-quarter profit alone reached RMB3.06bn, exceeding the company’s entire earnings for 2025.
Industry praise has been effusive. “They took the world by storm. What they’ve delivered so far has been excellent.".
Financial fireworks and industry scepticism
Yet scepticism lingers. Banchero Costa notes that 32.8% of all newbuilding contracting by cgt this year has gone to new or revived shipyards, predominantly in China. Hengli’s scheduled 2028 output, measured in cgt, is 3.5 times its annualised production rate for the first nine months of 2026. The broker warns that some deliveries may slip into later years, a concern echoed across the Chinese shipbuilding sector. Chinese yards are currently scheduled to deliver 89.1m dwt of bulk carriers and tankers in 2028, far exceeding their previous record of 62.6m dwt in 2011.
The gap between Hengli and its nearest rivals is vast. A year ago, Hengli ranked fifth globally with a 4.8% share. Its ascent has been nothing short of revolutionary.
Sign up free to ask CAMAL AI for a summary, the key points or anything else about this story.
Related stories
CAMAL AI
 Financial Ports Newsletter
The maritime economy, every morning
Ports, shipping and freight markets in one short email. Free.