US rail intermodal volumes jump 12.6% as diesel costs bite
Week 41 intermodal traffic surged 12.6% year-on-year, driven by high diesel prices and constrained truck capacity.
US intermodal rail volumes surged 12.6% year-on-year in week 41, the Association of American Railroads reported on Wednesday, as sustained high diesel prices and constrained truck capacity accelerated a road-to-rail freight shift.
The overall US rail traffic reading for the week climbed 8.5%, nearly three percentage points above the four-week moving average of 5.5%.
Why shippers are turning to rail: intermodal volumes
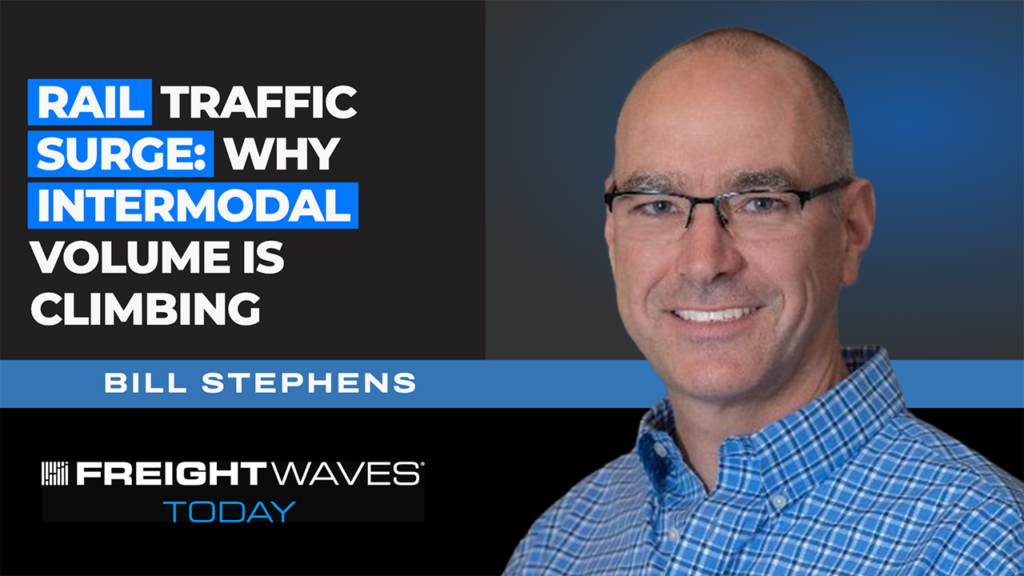
The primary catalyst behind the surge is the combination of elevated diesel fuel prices and a tightening trucking market. Bill Stephens, an industry analyst, stated:
“High diesel fuel prices and tight truck capacity has shippers diverting freight to rail.”
Bill Stephens·Industry Analyst
The shift is particularly pronounced in domestic intermodal, where railroads offer a cost-competitive alternative for long-haul freight.
The volume surge is already testing last-mile infrastructure. JB Hunt, a major intermodal carrier, highlighted difficulties in attracting sufficient drayage drivers to move containers to and from terminals.
Carload segments reflect industrial demand
While intermodal led the gains, carload traffic also posted a solid week, rising 3.5% in the US. The vast majority of commodity segments were in positive territory, with primary metal products standing out at a 25% increase. Within that category, coke traffic jumped 15.4%, metallic ores rose 7%, and iron and steel scrap climbed 9.1%, reflecting stronger steelmaking demand across both blast furnace and electric arc mini-mill operations.
Other notable gains included chemicals and petroleum shipments, up 2.6%, agriculture and food products, which rose 6.7%, and motor vehicles and parts, which posted a 5.6% weekly gain. Coal edged up 0.9%, while primary forest products were the lone laggard, down 10%.
The competitive landscape in domestic intermodal is also evolving. Following the announced merger discussions between Union Pacific and Norfolk Southern, rivals BNSF and CSX unveiled new interline intermodal partnerships. These agreements have pulled some domestic intermodal business away from Norfolk Southern toward CSX, a dynamic acknowledged by Norfolk Southern executives. However, year-over-year comparisons for Norfolk Southern are expected to normalise as the railroad begins lapping last year’s results.
On the pricing front, railroads have generally targeted rate increases one to two points above the rate of rail inflation. Fuel surcharge programs, which carry a built-in lag of roughly one to two quarters, are still adjusting to the recent fuel price spikes. Stephens noted there is “nothing to suggest” that the practice of pricing above cost inflation would change in the near term.
Wall Street analysts expect double-digit earnings-per-share growth for most Class I railroads in the third quarter, with the exception of Norfolk Southern, where consensus estimates call for approximately 5.5% growth.
Sign up free to ask CAMAL AI for a summary, the key points or anything else about this story.
Related stories
CAMAL AI
 Financial Ports Newsletter
The maritime economy, every morning
Ports, shipping and freight markets in one short email. Free.